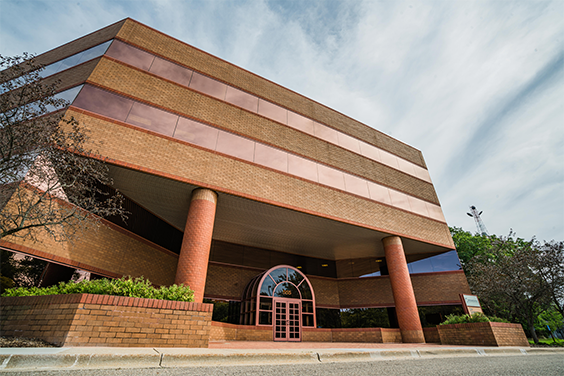
Our Kalamazoo office has moved! Our new location is 2725 Airview Blvd, Ste 300

Welcome to Seber Tans, PLC

Choosing the right accounting firm is one of the most important business decisions you will make. Any firm can add up the numbers and tell you where you’ve been, but Seber Tans will help you focus on where you want to go. In Southwest Michigan, the firm that unites professional expertise with creativity and vision is Seber Tans. With a team of experienced professionals on our staff, we can provide the capabilities of a large national organization, plus the personal attention of an independent firm. Clients choose us because we offer much more than off-the-shelf solutions. We will listen, ask questions, and learn all we can about your current situation. From that input, we’ll find creative solutions to help you focus on your opportunities rather than your obstacles. Join us and see why our clients trust us for their accounting, tax, and business advising needs.
Learn More

Seber Tans building

Services

With over 30 years of experience in providing clients with our accounting services, we are certain that we can provide you with the professional expertise you need.

Tax Services

Tax Services

Our clients turn to us for expert assistance to minimize their tax liabilities.

Client Accounting Services

Client Accounting

Our CPAs work with growing companies without internal CPAs or controllers.

Assurance / Auditing Services

Assurance / Auditing Services

We prepare financial statements & perform audits, reviews, and more.

Business Valuation Services

Business Valuation Services

We can provide business valuation services to our clients.

Information Technology Services

Information Technology Services

Our expert IT support team can handle your business’s technology needs.

Industries

We provide services for a variety of businesses, both big and small, and both for-profit and not-for profit. We provide excellent service at a reasonable cost so that nobody feels as if they have to go without financial advice. Seber Tans has worked with many companies in many different industries and has the knowledge and expertise that each different industry requires. Certainly, a not-for-profit company will operate differently than a construction company and will have different needs. Our goal is to specialize our services to exactly what you need. Give us a call today to find out how we can help.

Comments Box SVG iconsUsed for the like, share, comment, and reaction icons

5 tax-smart ways to take cash out of your C corporation

Paying dividends isn’t the only way to take cash out of your C corporation. Corporate distributions are generally taxable to you to the extent of your company’s “earnings and profits,” and your company can’t deduct them.

To avoid dividend treatment, consider having your business repay bona fide loans you’ve made to it or taking out properly structured loans from it. You might also increase your compensation (as long as it’s still “reasonable”) or qualifying tax-free fringe benefits — or lease or sell assets to your business.

Before proceeding, evaluate the tax implications for you and your corporation. Contact us to review the applicable rules and determine what’s right for your situation.
... See MoreSee Less

5 tax-smart ways to take cash out of your C corporation

Paying dividends isn’t the only way to take cash out of your C corporation. Corporate distributions are generally taxable to you to the extent of your company’s “earnings and profits,” and your company can’t deduct them.

To avoid dividend treatment, consider having your business repay bona fide loans you’ve made to it or taking out properly structured loans from it. You might also increase your compensation (as long as it’s still “reasonable”) or qualifying tax-free fringe benefits — or lease or sell assets to your business.

Before proceeding, evaluate the tax implications for you and your corporation. Contact us to review the applicable rules and determine what’s right for your situation.

Remote work can complicate your state taxes

If you work remotely and split your time between two states during the year, it can create state tax issues. A state with an income tax generally can tax all income of its residents and income earned within its borders by nonresidents. Residency rules vary but may consider your domicile, days spent in the state and whether you maintain a home there. Your domicile is generally your true, fixed, permanent home — the place you intend to return to. Some states may treat you as a resident for income tax purposes if you maintain a home and spend a specified number of days there. Contact us to review your situation and help determine whether you may have tax obligations in more than one state.
... See MoreSee Less

Remote work can complicate your state taxes

If you work remotely and split your time between two states during the year, it can create state tax issues. A state with an income tax generally can tax all income of its residents and income earned within its borders by nonresidents. Residency rules vary but may consider your domicile, days spent in the state and whether you maintain a home there. Your domicile is generally your true, fixed, permanent home — the place you intend to return to. Some states may treat you as a resident for income tax purposes if you maintain a home and spend a specified number of days there. Contact us to review your situation and help determine whether you may have tax obligations in more than one state.

Tax planning for real estate investors

Many individuals invest in real estate to help diversify their portfolio, create an income stream for themselves from rental income and build net worth over time. Income and losses from investment real estate are considered passive by definition — unless you’re a real estate professional. Even then, you generally must “materially participate” in a rental activity for it to be treated as nonpassive. Why is this important? Passive income may be subject to the 3.8% net investment income tax on top of any income tax otherwise due, and passive losses are deductible only against passive income, with the excess carried forward. Contact us to discuss tax planning for your investment real estate.
... See MoreSee Less

Tax planning for real estate investors

Many individuals invest in real estate to help diversify their portfolio, create an income stream for themselves from rental income and build net worth over time. Income and losses from investment real estate are considered passive by definition — unless you’re a real estate professional. Even then, you generally must “materially participate” in a rental activity for it to be treated as nonpassive. Why is this important? Passive income may be subject to the 3.8% net investment income tax on top of any income tax otherwise due, and passive losses are deductible only against passive income, with the excess carried forward. Contact us to discuss tax planning for your investment real estate.

Phone: 269.343.8180

Fax: 269.343.5419

Office Hours:
Monday – Thursday: 8:00am–4:30pm
Friday: 8:00am–12:00pm